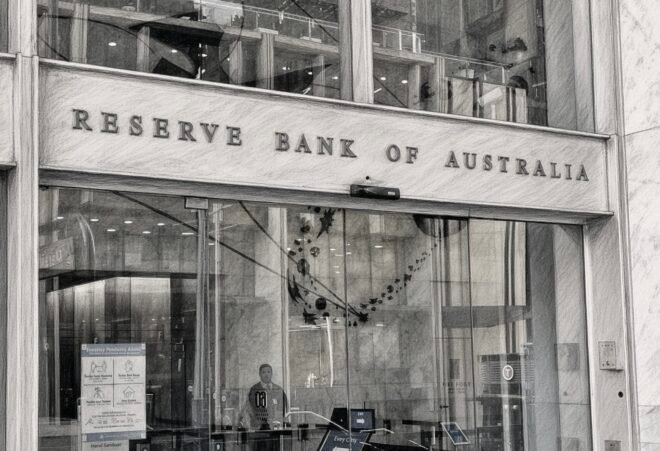
On 22 September, speaking to a business audience in Sydney, Reserve Bank Governor Michele Bullock said that unemployment would probably need to edge higher to help bring inflation under control. Her view was that a rate between 4.5 and 5 per cent would probably take enough heat out of the labour market to ease pressure on prices, though she stressed that there was no single figure the Bank was aiming for. A week later the Board lifted the cash rate to 4.60 per cent, the highest level since November 2011 and the fourth increase of 2026. The Governor’s language was careful, almost apologetic. But a careful number is still a number, and this one describes people who will be looking for work and not finding it. My argument is not that inflation is unimportant, or that the Governor is acting in bad faith. It is that the Bank is contemplating a rise in joblessness as the price of fixing a problem whose main causes lie largely outside its reach. That price will be paid by the people least responsible for the problem and least able to bear it. In that sense the Governor risks overstepping the mark.
The arithmetic of a “modest” rise
The headline figures are not in dispute. In August 2026 there were 722,900 unemployed Australians in seasonally adjusted terms, and the unemployment rate was 4.6 per cent. Employment stood at 14,836,600. Add the two and the labour force is about 15.56 million. A rate of 5 per cent would therefore mean roughly 777,975 unemployed people, about 55,000 more than today. Because the current rate is closer to 4.65 per cent before rounding, the real distance to 5 per cent is nearer 0.35 of a percentage point than 0.4. Either way, the percentage disguises the scale. Fifty-five thousand people is the working-age population of a sizeable regional city. Each of them has rent or a mortgage, dependants and a work history that will now carry a gap.
The slack in the labour market is also larger than the headline suggests. The underemployment rate in August was 6.2 per cent and the underutilisation rate was 10.8 per cent. That means roughly one in nine people in the labour force is either without a job or without the hours they need. Youth unemployment rose to 10.8 per cent. Over the past year the number of unemployed people has already risen by 80,000, or 12.4 per cent. The quality of the jobs being created matters too. In August, full-time employment fell by 6,300 while part-time employment rose by 45,800. A labour market described as tight at the policy table looks different to a person who cannot get a full week’s work.
There is an honest complication here, and the argument is stronger for conceding it. The recent rise in unemployment has not come mainly from layoffs. The ABS noted that a higher share of people who had been outside the labour force moved into unemployment this August, which pushed the participation rate up to 67.1 per cent. Economists at Judo Bank observe that the rise over the past six months has come almost entirely from higher participation rather than job losses, and the Governor herself has noted that a rising rate does not necessarily mean job losses. That is worth acknowledging, but it does not rescue the policy. Tighter monetary policy eases inflation by reducing demand, and reduced demand means fewer hires, fewer hours and, at the margin, fewer jobs. The people who meet the closed door first are those trying to enter or re-enter work: school leavers, carers returning to employment, people who have been out of the workforce for some time. A policy that works by making work harder to find is not neutral between those who hold a job and those who are looking for one.
Who stands in the path of the adjustment
Unemployment does not fall evenly. The pattern in every tightening cycle is that the adjustment lands first on casual and part-time workers, on young people, on those with fewer formal qualifications and on those living where alternative employment is scarce. For First Nations Australians, whose unemployment rate has long run well above the national figure, a cooling labour market compounds disadvantages that were already deep. These are the workers with the least bargaining power and the thinnest financial buffers. A redundant senior professional typically has savings, a network, credentials and the ability to wait for the right role. A low-wage worker in the same position often has none of these, and a missed rent payment or a small debt can become years of instability. Research on job loss consistently finds that a spell of unemployment depresses later earnings and can leave lasting scars. The same percentage rise in unemployment therefore carries very different human costs depending on where in the income distribution it falls. A policy that treats those costs as interchangeable is quietly assigning the heaviest share of the adjustment to those with the least capacity to carry it.
What is actually driving prices
The case for the Bank’s approach depends on what is pushing prices up, so that is the right place to examine it. Annual CPI inflation was 4.0 per cent in the twelve months to August 2026, up from 3.5 per cent in July, while trimmed mean inflation, the Bank’s preferred underlying measure, was 3.6 per cent. The ABS identified the main contributors to the annual rise. They were new dwellings, up 5.4 per cent, electricity, up 13.2 per cent, and rents, up 3.6 per cent. Housing inflation as a whole was 5.7 per cent, and transport was the second-largest contributor because of fuel. The fuel increase was abrupt. Automotive fuel rose 14.8 per cent in August alone, driven by higher world oil prices and the end of the federal government’s fuel excise relief. Electricity jumped after government rebates ended.
The Bank’s own account points the same way. Its September statement said there had been further disruptions to global oil supply, that higher fuel prices were partly being passed through to other goods and services, and that this came on top of capacity pressures in the economy. The Board’s minutes recorded discussion of structural factors that could explain lower supply capacity, including persistently weak productivity growth. At her press conference the Governor was blunt about it. She said productivity is doing nothing, and that monetary policy cannot do anything about it.
The Board’s argument deserves a fair hearing. If the economy’s capacity to supply goods, services and workers is not growing, then demand cannot grow strongly either without pushing up prices. The Board’s position is that growth in aggregate demand needs to stay subdued for a period to reduce capacity pressures and bring inflation back to target. There is something to this. Trimmed mean inflation at 3.6 per cent is above the target band even after the ABS has stripped out the volatile items, and fuel and electricity were both excluded from that measure. Some of the pressure is domestic and persistent.
A further factor is contested. The Australia Institute has argued for several years that corporate profit margins, rather than wages, drove much of the post-pandemic price surge. Its 2023 analysis attributed 69 per cent of inflation beyond the Bank’s target to excess corporate profits and only 18 per cent to rising unit labour costs. An OECD analysis of the five quarters to the end of 2022 found that higher unit profits accounted for an average of 51 per cent of the rise in the GDP deflator, against 21 per cent for unit labour costs. The Australia Institute says the OECD’s 2026 Employment Outlook extends that finding to late 2025 and early 2026. I have not seen the OECD’s 2026 text directly, and the Bank has been sceptical. Its own 2023 analysis found little evidence of a broad-based rise in non-mining profit margins, and concluded that domestic margins had not been a significant independent cause of aggregate inflation. The dispute is real, and a fair essay has to say so. Even the Bank’s version of events, though, places the main current pressures in oil, electricity, construction costs and productivity, and not in what workers are paid.
Why the interest rate is the wrong lever for most of this
Set what the ABS and the Bank describe against what a higher cash rate can do. The oil price is set in global markets, and no Australian rate decision will reopen a disrupted supply route. The Governor appeared to concede as much. She acknowledged that the current inflation stems from repeated supply shocks and that the interest rate as a tool does not seem sufficient unless the Bank is prepared to keep lifting it. That admission is the nub of the problem. If rates are raised far enough to suppress domestic demand by the amount needed to offset a global energy shock, the overshoot falls on domestic workers. And if oil supply recovers, headline inflation will fall anyway, and the unemployment incurred along the way will have been paid for a problem that was already passing.
Housing is the clearest case. New dwellings and rents are among the largest contributors to inflation, and both reflect a shortage of homes and the cost of building them. A higher cash rate does not reduce construction costs, train tradespeople or deliver dwellings. As one economist put it in response to the latest increase, higher rates can cool demand in the short term but can also make it harder to lift housing supply and address the long-term shortfall. The evidence has been accumulating. When the Bank raised the cash rate in February, data released the same day showed apartment approvals had fallen 29.8 per cent, and developers warned that higher financing costs would further undermine project feasibility. Industry analysis of the latest approvals data attributes soft multi-unit approvals to higher construction costs, elevated financing rates, slower presales and long planning timelines. I do not claim that rate rises push rents up directly, because CBA’s economists suggest investors’ higher costs may not be automatically passed on to tenants, who still constrain what landlords can charge. The point is narrower and harder to answer. Rate rises do nothing to add the homes whose shortage keeps rents and construction prices high, and they may delay those homes.
Productivity raises a similar problem. The Governor argues that the best contribution monetary policy can make to productivity is low and stable inflation, so that businesses and households can invest without fear of rising costs. That is a respectable argument about the long run. In the near term, though, a higher cost of capital is hardly an encouragement to the investment that lifts output per worker. The Board is asking the economy to slow while it waits for productivity to improve, and nothing in the policy tool hastens that improvement.
Then there is the question of who the tool actually reaches. Average rates on new owner-occupier home loans rose from about 5.50 per cent in January 2026 to about 6.25 per cent by mid-year. Households with mortgages feel that directly. Households with large deposits receive more interest. People at the bottom of the income distribution typically hold neither mortgages nor deposits of any size. They hold the risk of losing hours or a job. In effect the policy charges indebted households through repayments and charges the most marginal workers through jobs, while leaving those with substantial capital relatively insulated. Even by the Board’s own account, the three earlier increases have tightened financial conditions and the economy appears to be slowing. The question is whose spending is slowing, and who is being asked to stop.
Executive pay and the problem of shared sacrifice
Executive pay is not a cause of inflation. A few thousand senior executives cannot move the Consumer Price Index through their own spending. The objection is about fairness and about the public consent on which hard economic policy depends. The figures need careful handling, because the headline numbers circulating in this debate are older than they appear. A Governance Institute of Australia survey found that average fixed pay for ASX-listed chief executives rose 14 per cent and for managing directors 11 per cent, with medians of 11 per cent for CEOs and 5 per cent for managing directors, while general staff in listed companies received average fixed-pay increases of around 5 per cent. That survey was published in 2024 and covers 2023-24. Odgers Berndtson’s 2024 survey found S&P/ASX 300 CEO remuneration up 7.6 per cent, from $2.67 million to $2.87 million. Neither measures the current year.
More recent evidence points in the same direction without being uniform. Diligent reports that median granted pay for ASX 200 chief executives rose 9.8 per cent to $5.2 million in 2025, with realised pay up 10.6 per cent. The Australian Council of Superannuation Investors found that median realised pay for ASX 100 CEOs reached $4.8 million in FY25, the highest in the twelve years it has recorded, an increase of almost 16 per cent. Against that, an August 2026 briefing from Guerdon Associates reports that ASX 100 CEO remuneration increases were below inflation. The honest reading is that pay at the top of the largest companies has recovered strongly in realised terms but has not risen uniformly. That is enough for the argument made here. When the Bank signals that a measure of labour market pain is acceptable, and when business groups urge wage restraint on ordinary workers, the call for shared sacrifice is credible only if the sacrifice is visibly shared. It is difficult to ask a casual worker to accept a higher risk of redundancy while executive packages at the largest firms have reached record levels.
Overstepping the mark
None of this means the Bank should ignore inflation. Persistent inflation erodes the real incomes of the same low-income households, and the Bank holds a statutory mandate covering both price stability and full employment. It is also fair to remember that the Governor has not named 5 per cent as a target and has said a rise in the rate does not necessarily mean job losses. Central banks have few instruments, and the interest rate is the one they hold.
But that is precisely the difficulty. When the available instrument is blunt, the obligation to account for its distributional consequences grows heavier, not lighter. A Governor who tells the public that unemployment of up to 5 per cent would probably be enough owes them more than a technical range. She owes them an account of why this group of Australians should bear the burden, what protections will accompany it, and what other arms of policy are meant to deal with the causes the interest rate cannot reach. Those causes are a shortage of homes and the cost of building them, an energy system exposed to global shocks, years of stagnant productivity and, on some accounts, firms with the pricing power to widen their margins. They belong to governments, regulators and boards. They are not for the labour market to absorb.
An institution insulated from the consequences of its choices can overstep without bad faith. It need only come to treat an acceptable range of human hardship as an input to a model. The additional 55,000 people are not abstractions, and they will not come evenly from boardrooms and trading floors. They will come from the bottom of the income distribution, where a lost job is a crisis rather than an inconvenience. If Australia asks for sacrifice in the name of stability, that sacrifice has to be visible at the top as well as the bottom. And those who set policy have to defend not only the arithmetic of their targets but the justice of who is made to meet them.
– – –
Bakchos is the founder of Blak and Black, an Australian media and advocacy platform established in 2010. Bakchos writes from the intersecting perspectives of Wiradjuri heritage, Jewish identity, and humanism.
© Bakchos, October 2026